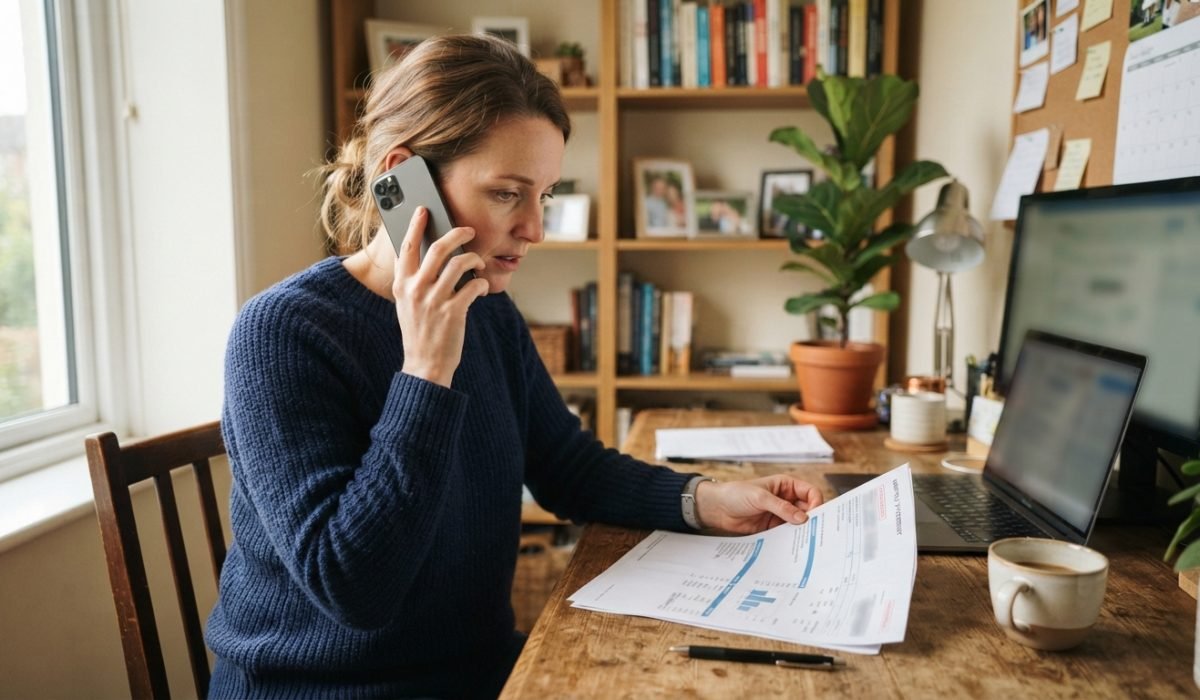
A mortgage prepayment penalty Canada quote is the number most homeowners only discover the day they phone their lender. It can be a few thousand dollars or it can be five figures, and which one you get depends on your rate type and when you signed.
There is one detail specific to 2026 that almost nobody factors in. Because rates rose after 2021, many borrowers who signed at 2% now face the small penalty rather than the large one.

How a mortgage prepayment penalty Canada is calculated
A mortgage prepayment penalty Canada comes in two shapes. On a closed variable-rate mortgage, it is three months of interest. Balance times rate, divided by four. It does not matter where market rates have moved.
On a closed fixed-rate mortgage, you pay the greater of three months of interest or the interest rate differential. The IRD is the gap between your rate and the rate the lender could charge now for the time left in your term, multiplied by your balance and the months remaining.
The Financial Consumer Agency of Canada sets out both methods on its prepayment penalties page, and notes that lenders generally use the IRD calculation when your rate is higher than the current rate and you signed the contract less than five years ago.
That is the sentence that decides everything. If rates today are higher than your contract rate, the gap is zero or negative, the IRD does not apply, and you pay three months of interest.
| Your situation | Which penalty applies |
|---|---|
| Closed variable | Three months of interest |
| Closed fixed, signed in 2021 at 2% | Three months of interest, because rates are now higher |
| Closed fixed, signed in 2023 to 2024 above current rates | Interest rate differential, usually the larger figure |
| Open mortgage | Usually no penalty |
| At renewal, not mid-term | No penalty |
Worked examples
Take a $400,000 balance at 2.29% with 20 months left, signed in 2021. Three months of interest is about $2,290. Current five-year pricing is higher than 2.29%, so there is no differential to charge. The mortgage prepayment penalty Canada figure here is the small one.
Now take a $500,000 balance at 5.79% with 24 months left, signed in 2023. If the lender compares against a 4.39% rate for the remaining term, the differential is 1.40% on $500,000 for two years, about $14,000. Three months of interest is about $7,240. The lender charges the higher amount.
A $520,000 closed variable at prime plus 0.20% with 18 months left pays about $6,500, whichever way rates move.
Why the same mortgage costs different amounts at different lenders
The mortgage prepayment penalty Canada formula looks fixed, but the comparison rate is not. The big banks generally use their posted rates, subtracting the discount you originally received from today’s posted rate for your remaining term.
Monoline lenders such as First National, MCAP and CMLS, and many credit unions, compare against the actual discounted rate instead. Reporting on 2026 penalty quotes puts big bank IRD figures at several times the monoline result on identical mortgages.
Disclosure rules require lenders to describe the components of the calculation, including the posted rate and the discount where those are used, as set out in FCAC Commissioner guidance CG-9. So the method is in your paperwork; it is just rarely read at signing.
That is a reason to ask about the penalty method at origination, not at the exit. If there is any chance of a job transfer, a separation, a sale or a refinance during the term, the method matters more than a five basis point rate difference.
Four checks before you break
- Get a written payout statement. Federally regulated lenders must provide one on request. It is free, usually arrives in one to three business days, and is the only number that counts.
- Ask about porting. If you are moving, a portable mortgage carries your rate and term to the new property and avoids the penalty entirely.
- Use your prepayment privileges first. Most mortgages allow 15% or 20% of the original balance annually. Paying that down before you break reduces the balance the penalty is calculated on.
- Check the break-even. Divide the penalty by the monthly saving from the new rate. If the answer is longer than the time left in your term, breaking rarely pays.
Timing tricks that actually work
Timing changes a mortgage prepayment penalty Canada quote. Prepayment privileges usually reset on your mortgage anniversary. Making a lump sum in December and breaking in January can let you use two years of privileges within a few weeks.
Penalties are calculated on the balance at payout, so the order of operations matters. Apply the lump sum first, get the new payout statement, then decide.
Ask whether the lender will add the penalty to a new mortgage. Most will, which spreads the cost but also means paying interest on it for years.
Two views on breaking a mortgage in 2026
The case for breaking now
If your mortgage prepayment penalty Canada quote is three months of interest because you signed at 2%, the cost of leaving is unusually low. That makes debt consolidation, a refinance for renovations or an early switch far cheaper than it was in 2021, when IRD penalties were brutal.
The case for waiting for renewal
Breaking a low-rate mortgage means giving up that rate. Refinancing a 2.29% balance into a 4.4% market rate costs real money every month, and the penalty is the smallest part of the arithmetic.
The honest test is the break-even calculation, not the size of the penalty. A small penalty on a great rate can still be a bad trade.
Tax treatment
On a principal residence, a mortgage prepayment penalty Canada is not deductible. On a rental property it generally is, as a financing expense, and a refinance for investment purposes may produce a partial deduction.
That is a question for your accountant rather than your lender, and it is worth asking before you sign the payout, not after.

Key takeaways
- A mortgage prepayment penalty Canada on a variable mortgage is three months of interest.
- Fixed mortgages cost the greater of three months of interest or the IRD.
- If current rates are above your contract rate, the IRD usually does not apply.
- Big bank posted-rate methods generally produce larger penalties than monoline contract-rate methods.
- Only a written payout statement gives you the real mortgage prepayment penalty Canada number.
What the payout statement will show
Ask for your mortgage prepayment penalty Canada figures itemised rather than as one total. A payout statement should show the outstanding balance, the penalty, accrued interest to the payout date, a discharge or administration fee, and any cash back you have to repay.
Cash back is the one that catches people. If you took a cash-back mortgage, breaking the term usually means repaying a prorated share of it on top of the penalty.
Your rights are set out in the FCAC guidance on mortgage prepayment rights. Federally regulated lenders must show prepayment privileges and charges in a single information box in your mortgage agreement, describe how the charge is calculated, and provide a written quote on request.
Statements are typically valid for a set number of days. If your closing date moves, request an updated statement rather than assuming the number holds.
Quotes from online calculators are estimates. Every lender uses its own posted rates and its own rounding for the comparison term, so a mortgage prepayment penalty Canada estimate can be out by thousands either way.
When breaking usually makes sense
Paying a mortgage prepayment penalty Canada charge to consolidate high-interest debt is the strongest case. Moving $40,000 of credit card balances at 20% into a mortgage at 4.4% saves enough monthly to cover a modest penalty quickly.
A separation or an estate settlement is the second. Here the penalty is a cost of the transaction rather than an investment decision, and porting is often unavailable.
Switching lenders purely for a lower rate is the weakest case mid-term, and the break-even calculation usually shows it. At renewal the same switch costs nothing, which is why most rate shopping should happen in the 120 days before maturity rather than in the middle of a term.
Frequently asked questions
How do I find out my exact penalty?
Call your lender or request a payout statement through online banking. Federally regulated lenders are required to provide one, and they must also give you a toll-free line where staff can explain the calculation.
Is there a penalty at renewal?
No. At maturity you can move to any lender without a penalty. The penalty applies only to breaking a term early.
Can I avoid the penalty by selling?
Not by itself. Porting the mortgage to the new property usually avoids it, if your lender allows porting and the new purchase qualifies.
Thinking about refinancing or switching? Compare Ontario mortgage rates and read our guide to renewals in 2027 before you request a payout.
Examples are illustrative and use Canadian semi-annual compounding. Penalty methods vary by lender; only your written payout statement is binding. Not financial advice.