Mortgage Renewal 2026 Canada: 7 Smart Ways to Beat the Payment Jump
A mortgage renewal 2026 Canada notice can be a shock if your last term started when 5-year fixed rates were under 2%. Many borrowers who locked in during 2021 are now renewing into rates around 4.4%. This guide shows what the jump looks like in dollars, what your options are, and how to cut the increase.
[rank_math_toc]
Why mortgage renewal 2026 Canada payments are rising
A 5-year term signed in 2021 comes up for renewal in 2026. Back then, many borrowers got fixed rates near 2%. In September 2026, the best 5-year fixed rates are around 4.39% and discounted variable rates are near 3.45%, based on nesto’s September rate update.
The Bank of Canada has held its policy rate at 2.25% since October 2025. That keeps prime at 4.45%. Fixed rates, though, rose over the summer as Government of Canada bond yields climbed.

What the payment jump looks like
Take a borrower with $450,000 left on the mortgage and 20 years remaining.
| Rate | Monthly payment | Change vs 1.99% |
|---|---|---|
| 1.99% (2021 fixed) | $2,273 | None |
| 3.45% (variable, prime minus 1.00) | $2,593 | +$320 |
| 4.39% (5-year fixed) | $2,811 | +$538 |
Payments are rounded and use Canadian semi-annual compounding. Your own numbers will depend on your balance, amortization and lender. Try our mortgage renewal calculator to see your figure.
What CMHC’s 2026 survey says about renewals
CMHC’s 2026 Mortgage Consumer Survey polled more than 4,100 Canadians who bought, renewed or refinanced in the 18 months before January 2026. Some findings:
- Borrowers who renewed saw payments rise by about $375 a month on average.
- 39% of mortgage holders said they worry about making payments, down from 53% in 2025.
- About 31% had cut or planned to cut other spending to keep up, with dining out the most common cut.
- 81% still see owning a home as a sound long-term investment.
Arrears remain low. The national 90-day arrears rate was 0.24% in Q4 2025, below the pre-pandemic level. See CMHC’s Residential Mortgage Industry Report for the wider market data.
Your mortgage renewal 2026 Canada options
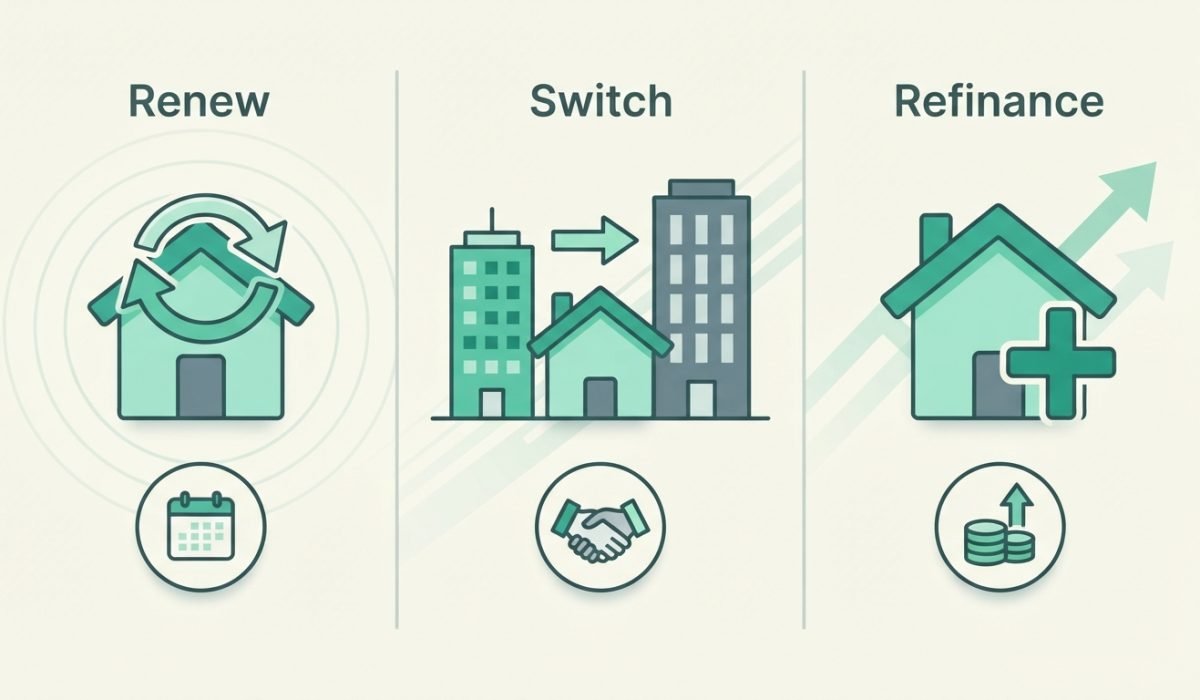
Sign your lender’s renewal offer
This is the easiest path, and it is often not the cheapest. The first offer in a renewal letter is frequently above the rate your lender gives new clients. Always ask for a better rate before you sign.
Switch to a new lender
Since November 2024, OSFI no longer requires a stress test for a straight switch of an uninsured mortgage at renewal. If you keep the same balance and amortization, you can move to a lender with a better rate without requalifying at a higher rate. Insured mortgages could already switch without a new stress test.
A switch may involve a discharge fee and legal or appraisal costs, though many lenders cover these to win the business.
Refinance
If you need to extend your amortization or roll other debt into the mortgage, that is a refinance. A refinance does trigger the stress test, and on an uninsured mortgage you can borrow up to 80% of the home’s value.

Fixed or variable for a 2026 renewal?
The spread between a discounted variable and the best 5-year fixed is close to one point. On the example above, that is about $218 a month.
- Variable fits if you can handle a payment increase and want the lower rate now. Most let you lock in later.
- Fixed fits if your budget has no room for surprises. The Bank of Canada warned in September about upside inflation risk.
- A 3-year fixed near 4.44% is an option if you expect rates to ease by 2029 and want a shorter commitment.
Seven ways to soften the increase
- Start 120 days early. Most lenders let you lock a rate that far ahead.
- Get at least three quotes, including one from a broker.
- Use the competing quote to negotiate with your current lender.
- Make a lump-sum prepayment on your renewal date, when penalties do not apply.
- Consider accelerated bi-weekly payments if cash flow allows. They shorten the amortization.
- If the payment is not manageable, ask about extending the amortization through a refinance.
- Pay down high-interest credit cards first so the mortgage payment is the only large fixed cost.
Mortgage renewal 2026 Canada checklist
- Find your maturity date on your last statement.
- Check your remaining balance and amortization.
- Note any prepayment privileges you have not used this year.
- Pull your credit report so there are no surprises.
- Gather your latest pay stubs and notice of assessment in case you switch.
- Compare rates on our Ontario rates page.
Renewal payment by balance
Here is the mortgage renewal 2026 Canada increase for two more balances with 20 years left, moving from a 1.99% term to a 4.39% fixed.
| Balance | At 1.99% | At 4.39% | Monthly increase |
|---|---|---|---|
| $300,000 | $1,515 | $1,874 | +$359 |
| $450,000 | $2,273 | $2,811 | +$538 |
| $600,000 | $3,030 | $3,748 | +$718 |
What a new lender checks when you switch
For many borrowers facing a mortgage renewal 2026 Canada payment increase, switching is the fastest saving. A straight switch skips the stress test, but the new lender still reviews your file.
- Your credit score and payment history.
- Proof of income, such as pay stubs, an employment letter or two years of notices of assessment if you are self-employed.
- The current value of the home, sometimes through an appraisal.
- Your current mortgage statement showing balance and remaining amortization.
Start the switch at least 30 to 45 days before maturity so the paperwork finishes on time.
Should you use a mortgage broker?
Why a broker can help
- One application reaches many lenders, including monoline lenders that do not have branches.
- Brokers are usually paid by the lender, so most renewals cost you nothing extra.
- They know which lenders accept switches with fewer conditions.
Why you might go direct
- Your bank may offer a relationship discount if you hold other products there.
- Some lenders’ best offers are only available in branch or online.
- You may prefer to keep everything with one institution.
Frequently asked questions
Can I change from fixed to variable at renewal?
Yes. Renewal is the one time you can change product type, term and lender without a penalty.
Is a shorter term better for a mortgage renewal in 2026?
A 2- or 3-year term can make sense if you expect rates to fall, but it exposes you to another renewal sooner. Match the term to how long you plan to stay in the home.
How early can I renew my mortgage in 2026?
Most lenders send a renewal offer 21 days before maturity, as federal rules require, but many let you renew or lock a rate up to 120 days early without a penalty.
Do I need a stress test to switch lenders at renewal?
Not for a straight switch with the same balance and amortization. A refinance or added borrowing does require one.
What happens if I miss my renewal date?
Many lenders roll you into a short open term at a higher rate. Renew or switch before the maturity date to avoid this.
Get a better renewal rate
A mortgage renewal 2026 Canada payment increase is real, but the first offer in your mailbox is not your only choice. Compare lenders on mrates.ca, secure a rate hold early, and use a competing quote to push your lender for a better deal.