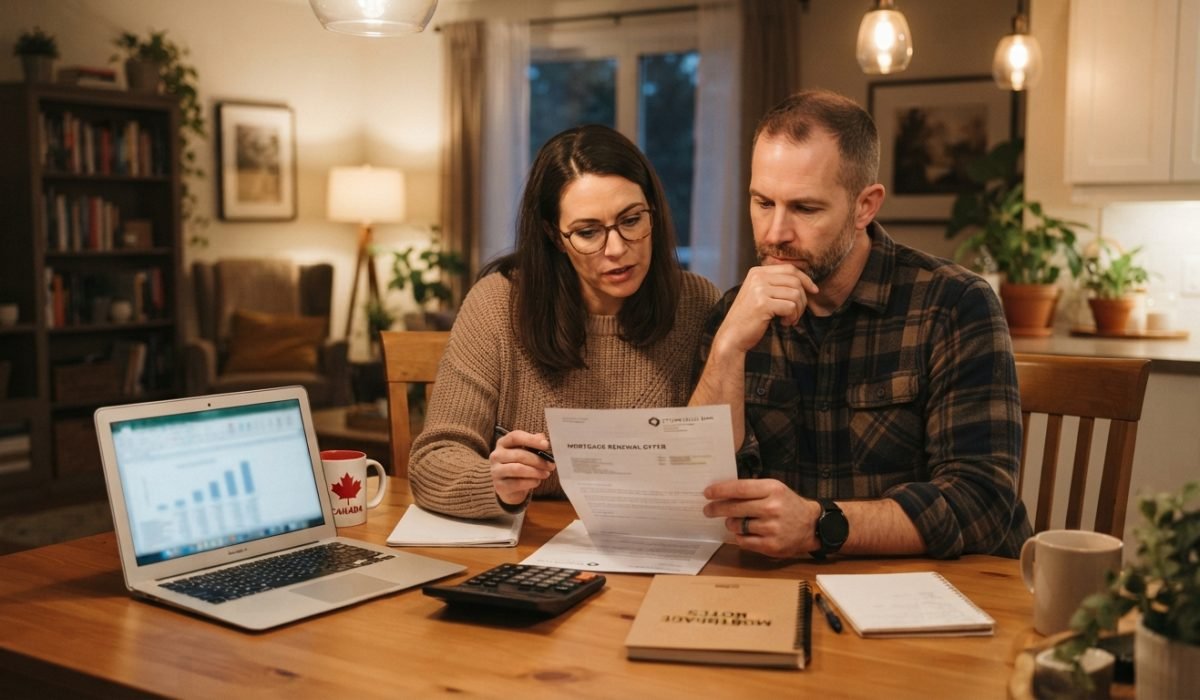

Mortgage renewal Ontario homeowners are one of the biggest stories in Canadian housing this year. About 1.15 million mortgages across the country come up for renewal in 2026, and a large share of them were signed when rates were near record lows.
If your term ends in the next few months, the renewal letter from your lender is probably going to ask for a bigger payment. Here is what to expect and how to keep that increase as small as it can be.
Why mortgage renewal Ontario looks different in 2026
Many homeowners locked in five-year fixed terms in 2020 and 2021, when the Bank of Canada ran emergency low rates and some borrowers got fixed rates under 2%. Those terms are now expiring.
The Bank of Canada’s own staff work estimated that five-year fixed borrowers renewing in 2026 could see payments rise by roughly 20% against their late-2024 levels. Ratehub’s analysis put a typical April 2026 renewal at about $622 more per month.
That is the core of the so-called renewal wave. It is not a market crash, but it is a real squeeze on monthly cash flow for a lot of households.
The numbers behind a typical renewal
Picture a $537,000 balance renewing at today’s best five-year fixed near 4.0%. The new payment lands around $3,260 a month, well above what the same borrower paid on a sub-2% term.
Even borrowers who signed in 2022 or later, at higher rates, may see only a modest change or a small drop this time. The pain is concentrated among the pandemic-era group.
You can read the Bank’s reasoning and current rate stance on the Bank of Canada site, which helps set expectations before you reply to any offer.
Do not just sign the first offer
The letter your bank sends is a convenience for them, not the best deal for you. Lenders know most people sign the renewal without shopping, so the rate on that page often has room to improve.
At renewal you can switch lenders with no penalty, because your old term has ended. That gives you leverage the bank does not advertise.
Getting a competing quote in hand, even one, tends to move your current lender. A broker can pull several at once and hand you the lowest.
Renew, switch, or refinance: the three paths
Renewing with your current lender is the simplest route. No new application, no appraisal, and you stay where you are. The catch is you may leave money on the table.
Switching to a new lender usually means a fresh application and a credit check, but it can unlock a lower rate. The new lender often covers transfer costs to win your business.
Refinancing is for people who want to pull equity, consolidate higher-interest debt, or change their amortization. It involves a full requalification, so plan the timing.
Smart moves for a mortgage renewal Ontario homeowners can use
Start four to six months out. Many lenders let you hold a rate ahead of your renewal date, so an early start protects you if rates climb before the deadline.
Ask about extending your amortization. Stretching the remaining years lowers the monthly payment, though you pay more interest over time. It can be a useful bridge if cash flow is tight this year.
Keep an eye on fixed versus variable. With the gap narrow in 2026, the choice comes down to whether you value a locked payment or a cheaper exit if you sell.
Watch your other debts. A clean credit profile and a lower balance help you qualify for the sharpest offers, so pay down what you can before you apply.
Is the renewal wave actually a crisis?
Most lenders and the CMHC describe it as a cash-flow challenge rather than a meltdown. The stress test that borrowers passed when they first qualified built in a buffer for exactly this.
Delinquency rates are still low, though they have ticked up slightly in high-priced markets like Toronto. The CMHC view is that most households will absorb the higher payment, even if it stings.
The takeaway is that a bigger payment is likely, but a well-planned renewal keeps it manageable.
Common questions about mortgage renewal Ontario
Can I switch lenders at renewal without a penalty?
Yes. Once your term ends you can move to a new lender with no break penalty, and the new lender often covers the transfer costs to win your business.
How early should I start a mortgage renewal Ontario lenders will honour?
Four to six months out is the sweet spot. Many lenders let you hold a rate ahead of the renewal date, which protects you if rates rise before your deadline.
Will my payment definitely go up in 2026?
If you signed a pandemic-era term under 2%, almost certainly. Borrowers who signed in 2022 or later at higher rates may see little change or even a small drop.
What if I cannot afford the higher payment?
Extending your amortization lowers the monthly amount, and a broker can compare lenders to find the lowest renewal rate. Starting early gives you the most room to adjust.
Get ahead of your renewal
A mortgage renewal Ontario borrowers handle early and with a few quotes in hand almost always beats one signed at the last minute. The difference can be hundreds of dollars a month over the next five years.
If your term is ending, compare your options at mrates.ca or book a renewal review before you reply to your lender’s letter.
L.K. Sharma is a licensed Mortgage Agent (Level 1) with Citadel Mortgage. This article is general information and not personal financial advice.