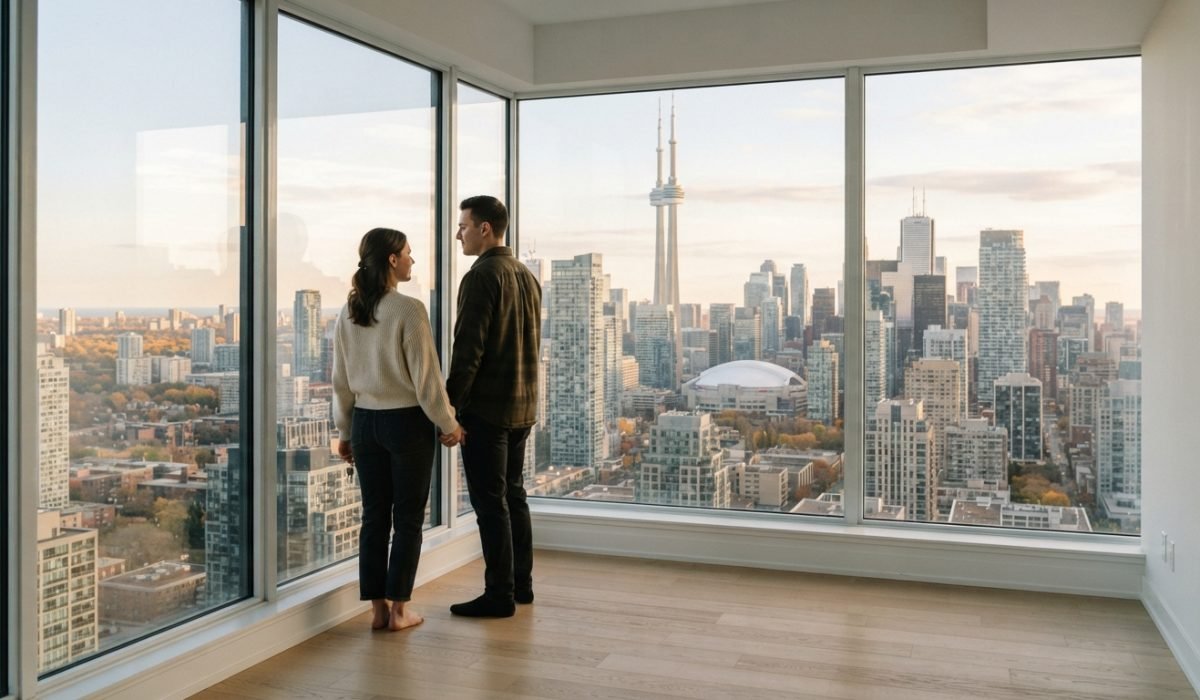

Toronto condo market numbers for September 2026 show a market that has tilted toward buyers. TRREB reported 1,316 condo apartment sales across the GTA in September, down 7.8% from a year earlier, and the average condo price fell 7.7% to $605,257.
For first-time buyers and investors, that raises two questions. Is this a good time to buy, and how do you avoid buying into a building or unit that keeps losing value? This guide covers the latest data, what a condo actually costs to carry each month, and the checks to run before you make an offer.
September 2026 snapshot: GTA condo sales 1,316 (down 7.8% year over year) | average condo price $605,257 (down 7.7%) | Toronto condo benchmark $527,200 (down 6%) | 8,226 condo apartments listed for sale at month end | Compare mortgage rates at mrates.ca
[rank_math_toc]
Where the Toronto condo market stands this fall
The broader GTA market has slowed along with the Toronto condo market. TRREB counted 5,040 home sales of all types in September, down 9% year over year, with an average price of $1,006,409 compared with $1,060,036 a year earlier. Condos are carrying more of the decline than houses. Detached and semi-detached sales were up year over year, while condo sales fell 7.8% and townhouse sales fell 12.8%.
Supply is the main reason the Toronto condo market is weaker. At the end of September there were 8,226 condo apartments listed in the GTA, according to Storeys’ summary of the TRREB data, with 5,329 in the City of Toronto and 2,897 in the 905 region. Many of those are investor units finished in the last two years, bought before rates rose.
1. Prices are lower than a year ago
The Toronto condo market benchmark price, which tracks a typical unit, was $527,200 in September. That is about 6% below September 2025 and 2% lower than three months earlier. The median price was $520,000.
For a buyer, a 6% drop on a $560,000 unit is about $33,000. That gap is real money, but it does not mean prices have reached a floor. Fixed mortgage rates have risen since early September, and CREA said on October 16 that it now expects Ontario’s average price to fall 3% for the full year.
2. Inventory gives you time to negotiate
Metro Toronto had about 6.3 months of condo inventory in September, according to Mortgage Sandbox’s September market update. That means it would take more than six months to sell every listed unit at the current pace of sales. Anything above roughly five or six months is usually considered a buyer’s market.
For buyers in the Toronto condo market, that means fewer bidding wars, more conditional offers, and sellers who will accept a home inspection, a status certificate review and a financing condition. Many of these conditions were hard to get in 2021 and 2022.
3. Monthly carrying costs are higher than the mortgage
In the Toronto condo market, the mortgage payment is only part of the cost. Here is an example for a buyer putting 10% down on a condo at the Toronto benchmark price of $527,200, with an insured 5-year fixed rate of 4.34%.
| Item | Amount |
|---|---|
| Purchase price | $527,200 |
| Down payment (10%) | $52,720 |
| CMHC premium (3.10%, added to the loan) | $14,709 |
| Total mortgage | $489,189 |
| Monthly payment, 25-year amortization | $2,664 |
| Monthly payment, 30-year amortization | $2,421 |
Estimates use standard Canadian mortgage math. In Ontario, 8% provincial sales tax on the CMHC premium is due in cash at closing.
On top of that, budget for condo fees, property tax and insurance. Condo fees vary widely by building, from a few hundred dollars to more than $1,000 a month. Ask for the exact amount and what it includes before you make an offer. Our CMHC mortgage insurance guide explains how the premium is calculated.
4. First-time buyers can use a 30-year amortization
First-time buyers can get an insured mortgage with a 30-year amortization. In the example above, that lowers the payment by about $243 a month. The trade-off is more interest over the life of the loan and slower equity growth. Our 30-year amortization guide has the full rules.
First-time buyers in Toronto also pay both the Ontario and Toronto land transfer taxes, but can claim rebates on each. On a $527,200 condo, each tax is about $7,019 before rebates. With the Ontario rebate of up to $4,000 and the Toronto rebate of up to $4,475, the total falls to roughly $5,563. Our Ontario land transfer tax guide walks through the calculation.
5. Check the building before the unit
In a soft Toronto condo market, the building matters as much as the price. A unit can look cheap because the building has problems that will cost you later. Ask for the status certificate and have a lawyer review it before your offer becomes firm. Look for:
- The reserve fund balance and the most recent reserve fund study
- Any special assessments announced or under discussion
- Planned increases to condo fees
- Lawsuits involving the condo corporation
- Rental restrictions, if you plan to rent the unit out
Buildings with a high share of investor owners can see more price swings, because many owners try to sell at the same time.
6. Unit size and layout affect resale
The steepest declines in the Toronto condo market in recent years have been in small studios and one-bedroom units, especially in the 905 region. Larger units with two bedrooms, two bathrooms and parking have held value better, because they appeal to families and long-term owners rather than investors.
If you plan to live in the unit for five years or more, a functional layout and parking can make resale easier when you move on. A unit with a den that can work as a second bedroom is often a good middle ground on price.
7. Get your rate held before you shop
Fixed rates have moved up since September. BMO and CIBC raised 5-year fixed rates in early October, and the Bank of Canada makes its next decision on October 28. A pre-approval with a rate hold protects your rate for 90 to 120 days at most lenders, which gives you time to shop in a slow Toronto condo market without worrying about rates rising under you. You can test your budget first with the mrates.ca mortgage calculator.
Should you buy in the Toronto condo market now?
There is no single right answer, so here are both sides.
The case for buying now
- Prices are below last year’s levels, and sellers are open to conditions and price negotiation.
- High inventory in the Toronto condo market means you can compare several buildings before deciding.
- CREA expects sales to recover in 2027, so buyers who wait may face more competition.
- Each mortgage payment builds equity, while rent builds none.
The case for waiting
- Prices are still falling, and CREA expects Ontario’s average price to end 2026 lower.
- Fixed rates have risen and the Bank of Canada may raise its policy rate, which would reduce what you can borrow.
- Rents in Toronto are also falling, so renting for another year is cheaper than it was.
- New supply is still being completed, which could keep pressure on prices for small units.
Buyers who plan to stay five years or longer in the Toronto condo market and can carry the full monthly cost are in a better position to buy now than short-term investors are.
Frequently asked questions
Are Toronto condo prices still falling?
Yes. The Toronto condo benchmark price in September 2026 was $527,200, about 6% lower than a year earlier and 2% lower than three months earlier.
Is the Toronto condo market a buyer’s market?
Based on inventory, yes. Metro Toronto had about 6.3 months of condo inventory in September, and GTA condo sales were down 7.8% year over year.
How much down payment do I need in the Toronto condo market?
The minimum is 5% on the first $500,000 and 10% on the portion above that, up to $1.5 million. On a $527,200 condo, the minimum is $27,720.
What should I check before buying a condo?
Have a lawyer review the status certificate, including the reserve fund, special assessments, planned fee increases and any lawsuits.
Talk to a mortgage agent before you make an offer
Before you shop the Toronto condo market, a short call can show you what you qualify for and which lenders treat condo purchases well. Contact mrates.ca to compare rates and get a pre-approval with a rate hold. You can also read our GTA housing market outlook for the wider picture.
By L.K. Sharma, Mortgage Agent Level 1, Citadel Mortgage. This article is for general information only and is not financial or legal advice. Figures are from TRREB data reported for September 2026 and are current as of October 23, 2026.